Right-Sizing 55+: Sell Big, Live Smaller, Retire Better in Singapore
By Daniel Wu, CEA Reg No: R070500C | Updated November 2026
Right-sizing is not downgrading. It is turning a home that is too big, too costly to maintain, and too much lease to use — into cash, CPF payouts, and a home that fits the next 20 years.
Q1. Should I right-size at 55+ — and when?
Right-size when the house no longer fits the life: spare bedrooms you clean but never use, stairs you avoid, maintenance and conservancy you pay for space you do not need, and most of your wealth locked in one flat while your monthly retirement income is tight.
Do not right-size just because you turn 55. 55 is when the options open — Silver Housing Bonus, short-lease 2-room Flexi — not a deadline. The right time is when you can answer yes to two questions: (1) will the move free enough cash / CPF to change your monthly income, not just give you a one-off lump sum? (2) will the smaller home still fit you at 75 and 85 — lift, no stairs, near family, clinic and MRT?
If you love your home, your neighbours and your area, staying put may be right — see Q4, Lease Buyback. If you are cash-tight but house-rich, moving is usually the stronger option, because the price gap between flats is bigger than any bonus.
Q2. How much cash does right-sizing actually free up?
The bonus is not the money. The price gap is. Example, illustrative only, using September 2026 medians from PLB Research / data.gov.sg: HDB resale median $565,000, 4-room median $533,000, 5-room median $675,000.
Source: PLB Research market tiles, Sep 2026, HDB resale via data.gov.sg.
Illustrative: sell a 5-room at the $675,000 median and buy a 4-room at the $533,000 median, and the gap is about $142,000 before costs — before CPF refund, agent commission, legal fees, renovation and moving. That is my own arithmetic from those medians, not a promise for your flat. Your actual gap depends on your block, floor, lease left, condition and timing.
Check your own numbers first: what is your flat worth today, what will the smaller flat cost, what must go back to CPF with accrued interest at 2.5% p.a., and what is left in cash after all costs?
Source: CPF Board, CPF refund + accrued interest 2.5% p.a. compounded monthly.
If the net cash after costs is small, the move may not be worth the disruption — even with a bonus.
Q3. What is the Silver Housing Bonus — up to $40,000?
The Silver Housing Bonus (SHB) rewards you for selling a bigger home and moving to a 3-room or smaller HDB flat. Enhanced from 1 December 2025: up to $40,000 cash per household.
How it works: base bonus up to $30,000 — $1 for every $2 of net increase in your CPF Retirement Account, on up to $60,000. Plus an extra $10,000 if you move to a 2-room or smaller flat, including a Community Care Apartment. Maximum $40,000 per household. The CPF top-up can often come from the CPF housing refund your sale itself generates, so a cash top-up may not be needed.
Source: HDB.
Who qualifies: at least one Singapore Citizen owner aged 55 or older, gross monthly household income $16,000 or less — raised from $14,000 on 23 Aug 2026 — the flat you sell has met MOP, or a private home with annual value up to $31,000, and the flat you buy is a 3-room (excluding 3-room terrace) or smaller. You must join CPF LIFE.
Source: HDB / MND, Aug 2026.
Important: a move from a 5-room to a 4-room does NOT qualify for SHB — it must be to a 3-room or smaller.
Q4. What is the Lease Buyback Scheme — and when is staying better?
The Lease Buyback Scheme (LBS) lets you sell part of your flat's remaining lease back to HDB and keep living in it. You stay in your home, your neighbours and your area — and you get retirement income instead of moving.
Who qualifies: all owners aged 65 or older, at least one Singapore Citizen owner, gross monthly household income $16,000 or less, no private home, at least 5 years living in the flat (10 years for Plus / Prime flats), and at least 20 years of lease left to sell.
Source: HDB.
Bonus: up to $30,000 for a 3-room or smaller flat, $15,000 for a 4-room, $7,500 for a 5-room or bigger. The full bonus needs a total Retirement Account top-up of at least $60,000, otherwise it is pro-rated. After meeting the required top-up, a household can keep up to $100,000 of the proceeds in cash.
Source: HDB.
Most proceeds go into your CPF Retirement Account and CPF LIFE for lifelong monthly payouts — LBS is a retirement-income scheme, not a lump-sum cash-out.
You can take the SHB bonus OR the LBS bonus, never both.
Source: CPF Board, retirement sums 2026.
Choose stay or move first, then pick the scheme — do not plan around both bonuses.
Q5. What about CPF at 55 — how much do I need, and what will I get monthly?
At 55, CPF sets aside a retirement sum in your Retirement Account. For members turning 55 in 2026: Basic Retirement Sum $110,200, Full Retirement Sum $220,400, Enhanced Retirement Sum $440,800.
Source: CPF Board, retirement sums 2026.
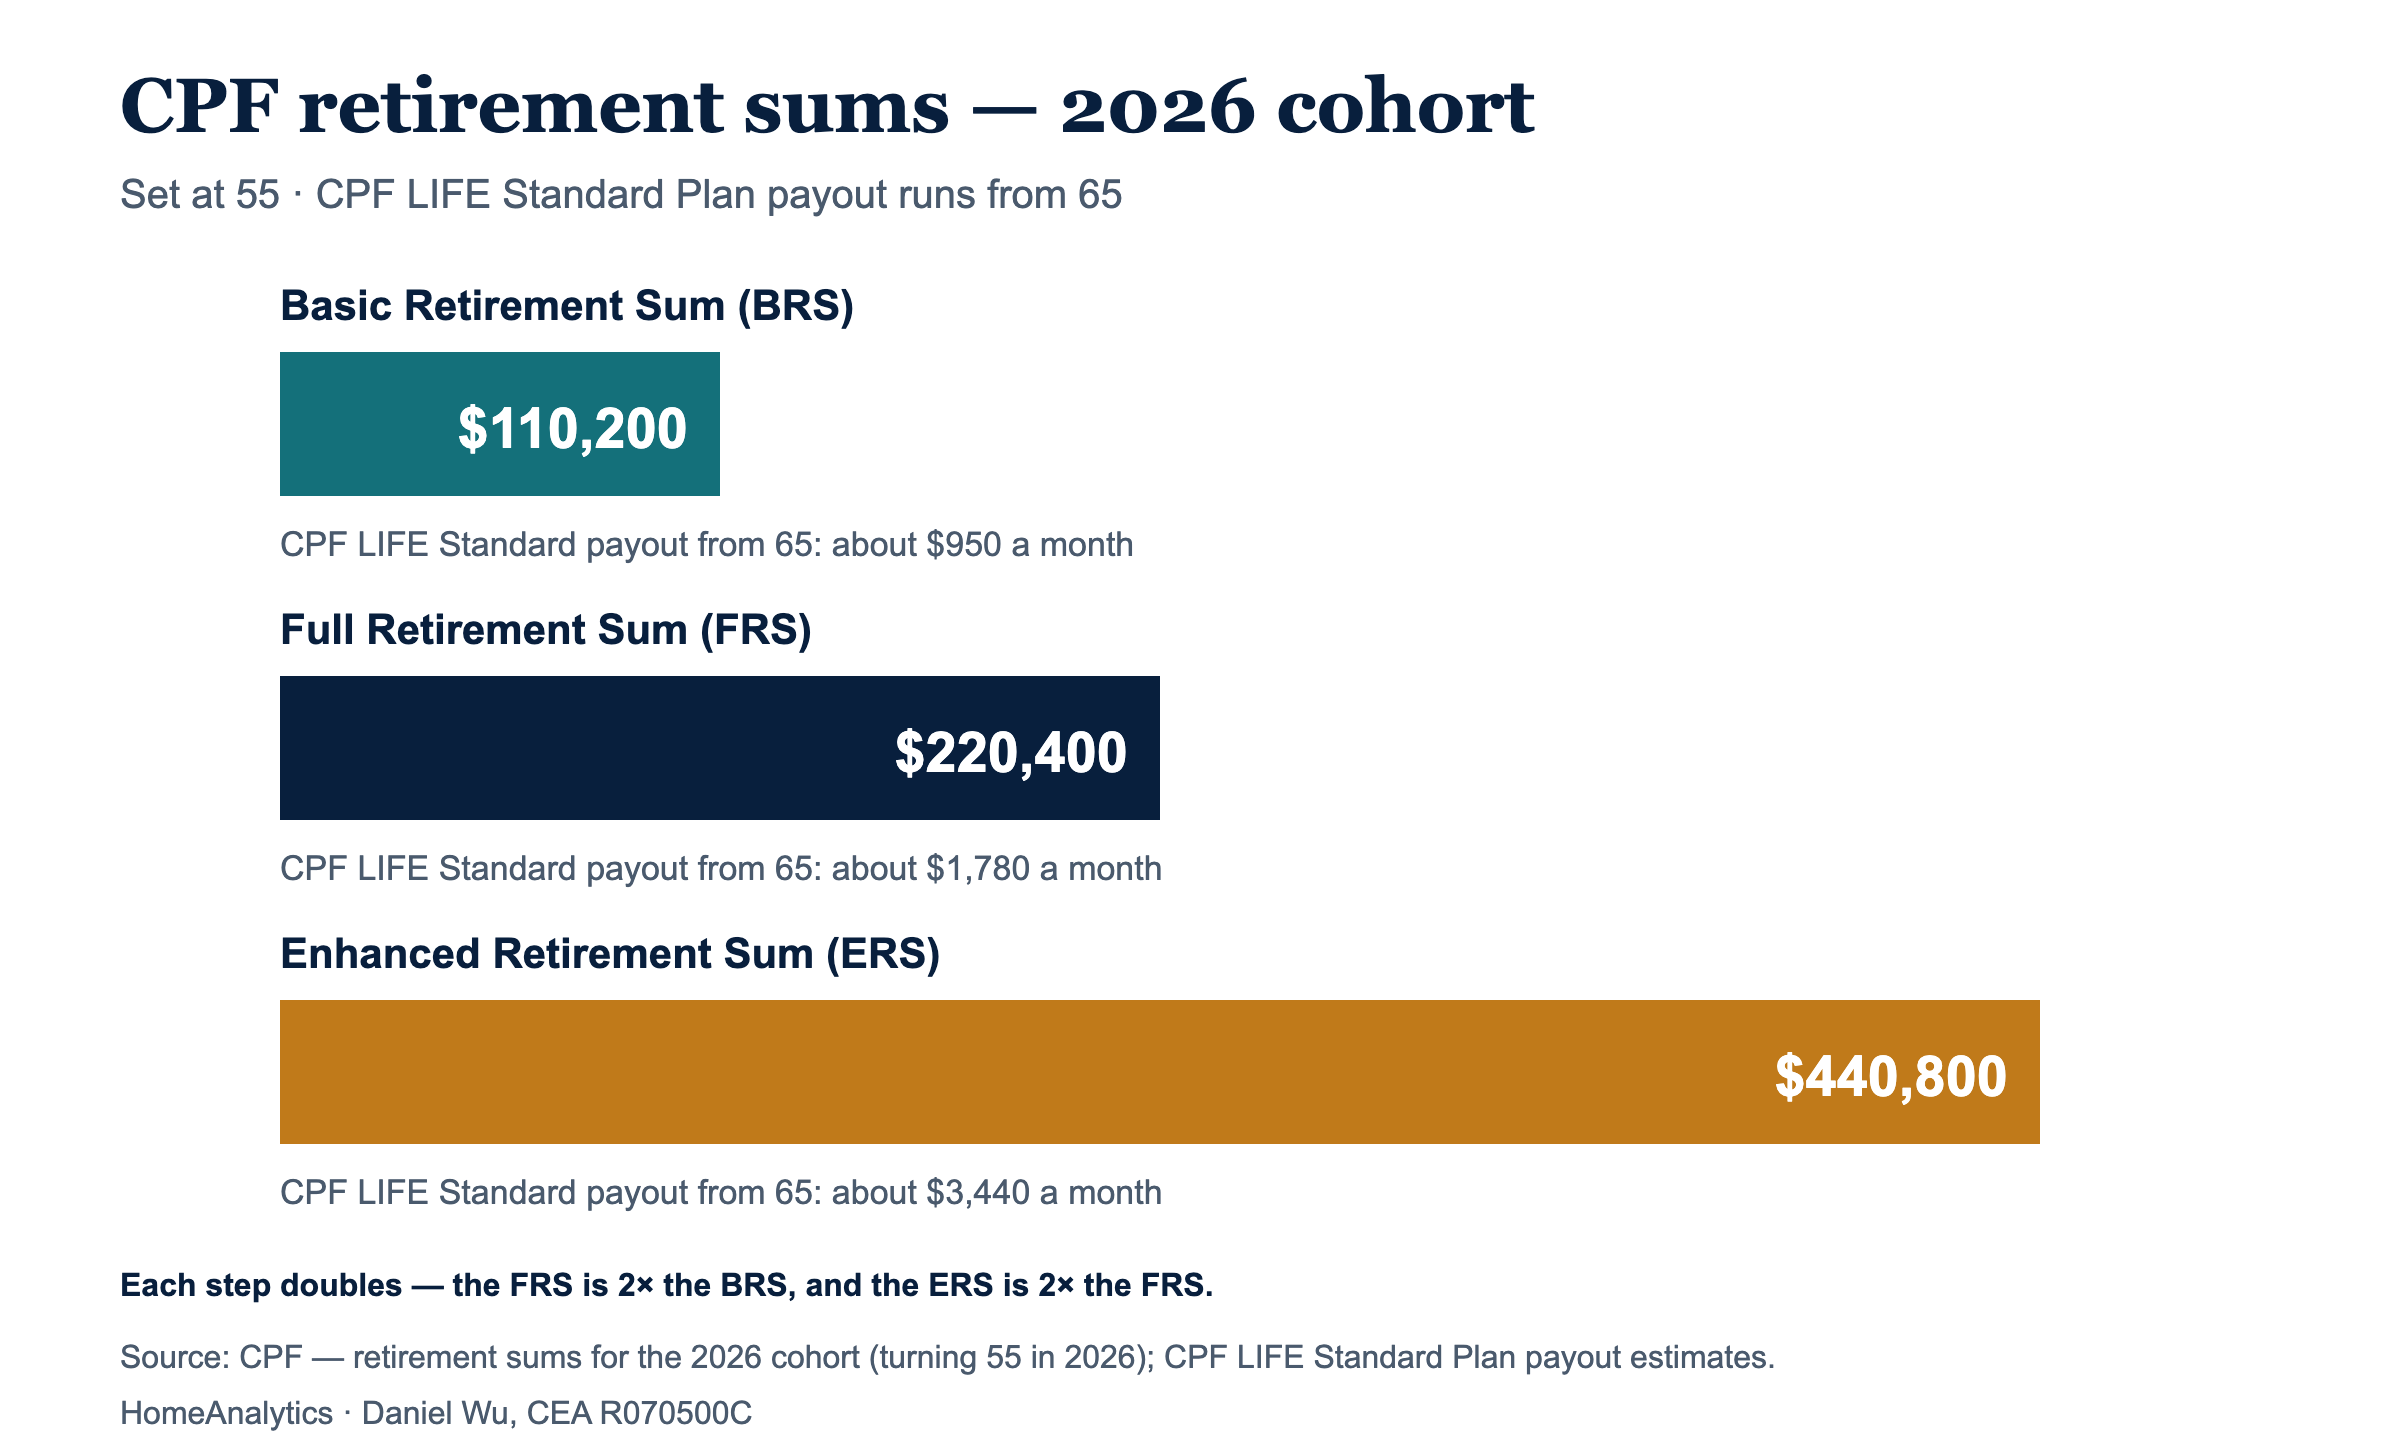
CPF retirement sums for the 2026 cohort: BRS $110,200 · FRS $220,400 · ERS $440,800 — with CPF LIFE Standard payouts from 65 of about $950, $1,780 and $3,440 a month. Source: CPF.
Estimated CPF LIFE payouts from age 65, Standard Plan, male member: BRS about $950 a month, FRS about $1,780 a month, ERS about $3,440 a month.
Source: CPF Board, monthly payout estimates, Oct 2026.
Those are estimates, not guarantees — they vary by plan, gender, interest rates and life expectancy. Your BRS / FRS is locked in at the year you turn 55.
Right-sizing helps CPF in two ways: the sale refund goes back to CPF, and the SHB / LBS top-up raises your Retirement Account, which raises your CPF LIFE payout. But check first: will your payout cover your actual monthly spending? If FRS gives about $1,780 a month and your spending is $2,500 a month, you still have a gap — and a smaller flat with lower maintenance helps close it, but it does not close it alone.
Q6. What is a short-lease 2-room Flexi flat — and is it a trap?
A short-lease 2-room Flexi is a 1-bedroom HDB flat for Singapore Citizens aged 55 and above, on a lease of 15 to 45 years in 5-year steps, as long as it covers you and your spouse to at least age 95.
Source: HDB, 2-room Flexi.
Example: if the younger of you is 65, the lease must run at least 30 years (95 minus 65), so 30, 35, 40 or 45 years are open. If the younger of you is 55, only 40 or 45 years qualify. HDB adjusts the price to the lease you choose — a shorter lease costs less, which frees up cash and CPF.
Source: HDB / PLB Research, Sep 2026.
It is not a trap, but know the trade-offs: no HDB loan on a short-lease flat — you pay with cash or CPF. Any existing flat or private home must be sold within 6 months of completing the purchase. Income ceiling $16,000 for a short-lease flat, for HFE applications from 24 Aug 2026.
Source: HDB.
And a short-lease flat has almost no resale value at the end of its lease — you are buying a home to live in, not an investment to sell on.
Community Care Apartments are similar, built for seniors with care services on site and a compulsory Basic Service Package. Minimum age was 65, dropping to 55 from the next BTO exercise, moved to November 2026, including a CCA project in Toa Payoh.
Source: HDB, via PropertyNet / PLB Research, Sep–Oct 2026.
Check HDB for the current BTO list before deciding.
Still unsure whether to stay, move, or sell back your lease? DM "55" + your flat type, your age, and whether you want to stay or move, and I will run your numbers — or book a free Personalised Property Consultation via homeanalytics.sg.
Daniel Wu | CEA Reg No: R070500C
General information only as at Nov 2026, not financial / legal advice. Check HDB / CPF / IRAS / MAS before deciding.
Sources: CPF Board, HDB, MND, PLB Research / data.gov.sg.